Market Views
EXPO REAL 2026 | A Slow Recovery and Expanding Real Estate Investment Landscape
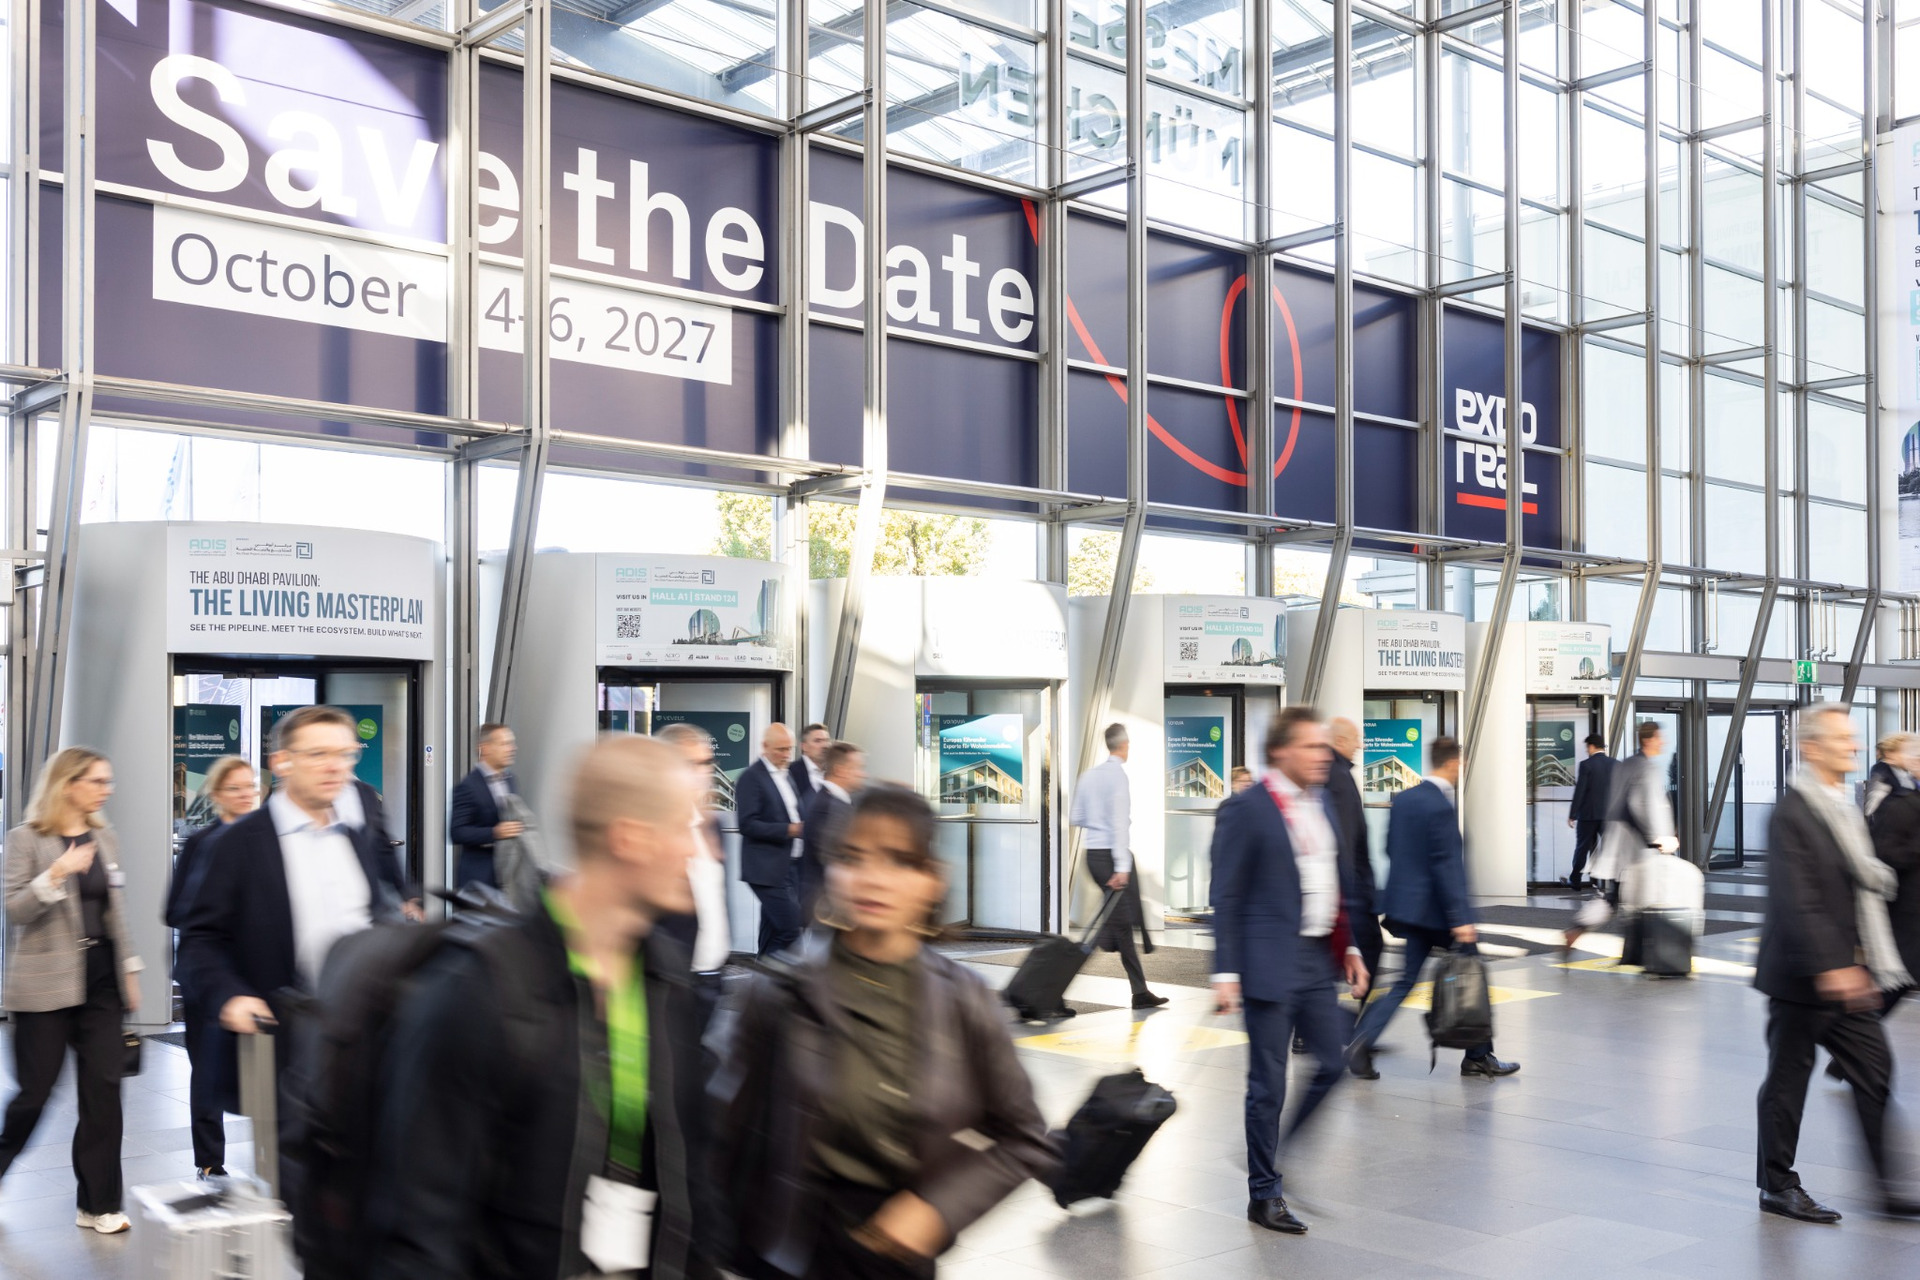
EXPO REAL 2026, held in Munich this October, highlighted two key trends. While recovery across global real estate investment markets has been slower than anticipated, investors are increasingly looking beyond conventional property sectors towards opportunities intersecting real estate and infrastructure. Investor sentiment has fluctuated considerably over the past year. At EXPO REAL 2025, expectations of interest rate cuts supported cautious optimism that the market was beginning to turn a corner. The mood was increasingly positive by MIPIM in March, backed by increased transaction activity. Seven months later at EXPO REAL, however, sentiment has once again returned to a more cautious stance. Though meeting schedules remained active, capital for deployment remained limited. Investors appeared increasingly selective, scrutinizing potential risk and returns more closely and taking longer to commit capital. Despite this backdrop, there was evidence investors were continuing to explore new strategies, particularly at the intersection of real estate and infrastructure. EXPO REAL reflected this shift in the introduction of infrastructure as an exhibition category for the first time this year. Asset quality alone is no longer enough The gap between bid and asking prices remains evident, further stalling recovery of the investment market. The best assets in prime locations do not always meet exit pricing expectations. Discussions during EXPO REAL provided insight into this mismatch. A European logistics platform owned by an institutional investor had sought to sell its prime logistics assets over the past year. The assets included newly completed logistics facilities secured by leases of more than ten years to high-quality corporate tenants. Despite meeting many of the criteria typically favored by institutional investors, the sale was reportedly withdrawn after failing to attract bids at their target pricing levels. The investor in this case benefits from long-term capital backing and has the flexibility to retain the assets. Not all investors are in the same position. Some German open-ended real estate funds, for example, have reportedly been considering asset disposals to meet rising redemption requests and manage liquidity. However, bid pricing potentially falling below current valuations remains a structural constraint to exit. In the current market, how long an underlying investor can afford to hold an asset matters as much as the quality of the asset itself. Looking ahead, more investors may need to reassess pricing expectations and consider disposals as they respond to upcoming debt maturities and investor redemption requests. Capital is becoming more selective Over the past three years, family offices and high-net-worth individuals (HNWIs) have been amongst the most active participants in European real estate investment markets. While large institutional investors remained cautious of new commitments, family offices and HNWIs were often able to move more quickly and take advantage of pricing adjustments. At this year's EXPO REAL, however, I was repeatedly informed of family offices and private investors reassessing or hitting pause on transactions, or putting new investments on hold. EXPO REAL 2026 © IGIS Europe Large global investment managers and some sovereign wealth funds still have substantial deployable capital, but allocation remains highly selective. Some Asian investors are prioritizing their domestic markets or geographies they know well, while German institutions appear increasingly focused on select sectors, particularly residential assets in their home markets supported by strong structural supply-demand imbalances. Private capital from Central and Eastern Europe, including Poland and the Czech Republic, is showing particular interest in expansion into Western Europe. One Czech investment manager, which has grown with the backing of several Czech family offices and HNWIs, is one such example. Capital seeking investment opportunities has not disappeared. Rather, investor preferences have become more selective and differentiated across geographies and sectors, making the path from initial interest to capital commitment and transaction execution increasingly challenging. Could European real estate transaction activity pick up in 2027? At this year's EXPO REAL, some market participants suggested that European real estate transaction volumes could begin to rise in 2027. An increase in transaction activity, however, would not necessarily signal a broader market recovery. Some investors who have deferred disposals over the past several years may face growing pressure to exit as they approach debt maturities, fund liquidations, or investor redemptions. In particular, funds and investors may need to consider asset sales or recapitalisations as their investment periods approach expiration. For buyers with deployable capital, these circumstances could present attractive acquisition opportunities at adjusted pricing. However, transactions will depend on sellers adjusting their pricing expectations and buyers being able to achieve acceptable returns reflecting prevailing high interest rates and cost of capital. Against this backdrop, 2027 could mark a period of renewed transaction activity accompanied by more meaningful asset repricing and capital structure adjustments. Infrastructure takes center stage: a first in EXPO REAL’s 28-year history One of the most notable developments at EXPO REAL 2026 was infrastructure being a major exhibition area for the first time in the conference’s history. This reflects increasing investor appetite for this asset class and the shift in how investors define the real assets universe. The exponential growth of artificial intelligence and the energy transition are driving greater demand for infrastructure investment. Demand for data centers is accelerating alongside growth of AI and cloud computing. Access to sufficient power capacity and reliable energy infrastructure has become as critical as location in development decisions. EXPO REAL 2026 © Messe München GmbH Logistics and industrial facilities are becoming increasingly automated and office buildings more digitally enabled. Power availability and supporting infrastructure play a central role in accommodating these shifts and influencing how properties operate and retain value. At the same time, Europe requires substantial investment to fund its energy transition, address ageing infrastructure, and meet its ambitions for defense and industrial capacity. Private capital is likely to play an increasingly important role in supplementing public funding. In an interview with Green Street News during EXPO REAL, the CEO of a German investment manager described this trend as an "infrastructure supercycle", suggesting a long-term structural shift rather than a temporary investment theme. These developments also invite us to reconsider the traditional distinction between real estate and infrastructure. A data center, for example, is a real estate asset in physical terms, but its investment performance depends heavily on power infrastructure, technical requirements, and operational capabilities. Real estate investment managers will therefore need to broaden their expertise beyond traditional property sectors, developing a deeper understanding of energy, technology, and operating businesses. Infrastructure, of course, differs from conventional real estate in its risk profile, investment horizon, capital requirements, and operational complexity. Entering these markets requires careful preparation and specialized expertise. Nevertheless, the shift evident at EXPO REAL raises an important question for real estate investment managers: how can we build on our existing capabilities to expand into new areas of investment? Emerging investment themes: from interest to execution EXPO REAL 2026 featured a broad range of investment opportunities, including purpose-built student accommodation (PBSA), senior living, data centers, grocery-anchored retail parks, and mid-box industrial properties. Interest in defense-related real estate was also evident, reflecting increased defense spending across Europe. However, there remains a considerable gap between enthusiasm for an investment theme and the ability to execute a transaction. Investors are looking for more than a compelling structural growth story. They increasingly want evidence from comparable transactions, actual rental income and operating costs, and a a credible exit strategy, which can be difficult to establish in the current market. This also presents a particular challenge for niche sectors where institutional investment markets are not yet well established. Limited transaction histories can make underwriting more difficult. New markets require early investors to support their development, yet those same investors often seek established transaction records and proven return profiles before committing capital. It is a familiar dilemma. A question raised in an industry commentary about strategies promising attractive returns from emerging investment themes has stayed with me: "It sounds compelling, but who will buy the asset in five years?" It is an especially relevant question in a market where liquidity remains constrained. However attractive the initial business plan or projected returns may appear, realizing those returns becomes difficult without a credible pool of buyers at exit. This is why assessing an emerging investment sector requires more than evaluating its growth potential. Investors must scrutinise actual cash flows, operational capabilities, and whether the sector can eventually mature into a mainstream institutional investment market. AI and operational expertise: the changing drivers of competitive advantage At last year's EXPO REAL, there was a noticeable increase in companies showcasing PropTech and AI-driven solutions. This year, the conversation had moved further toward practical applications—how these technologies could be integrated into day-to-day investment and asset management. Global investment managers are increasingly adopting AI-enabled platforms across lease administration, operating cost analysis, energy optimization, and investment decision-making. What stood out to me was the potential to bring together information that has traditionally been fragmented across individual properties and teams, making it accessible and actionable across an organization. This represents an opportunity to move beyond incremental improvements in efficiency and turn years of accumulated investment experience and proprietary data into a more scalable source of competitive advantage. Companies sharing exhibition booths at EXPO REAL 2026 © IGIS Europe The growing use of AI also coincides with a broader shift toward operational expertise in real estate investing. Operational real estate was a prominent topic at MIPIM this March, reflecting an environment in which the drivers of investment performance are evolving. As interest rates and capital costs have changed, investors are placing greater emphasis on generating stable cash flows and creating value through operational improvements, rather than relying primarily on market-driven capital appreciation. Ultimately, investment performance may depend as much on selecting the right assets, choosing the right operating partners, and delivering measurable value creation as it does on identifying the right sectors. From waiting for recovery to preparing for change One of my strongest impressions from EXPO REAL 2026 was that, even as transaction markets continue to adjust, the range of real assets available for investment and management is expanding. This presents new opportunities while also changing the expertise required of investment managers. Identifying quality assets and acquiring them at the right price remain essential. Increasingly, investment managers must also bring a deeper understanding of emerging industries, specialized operational expertise, capital structuring capabilities, and the ability to leverage technology and data. This calls for an investment approach that considers operational performance, value creation, and exit opportunities from the outset. At IGIS Asset Management, we have been building on our investment and asset management experience in Korea while combining it with local expertise and networks in overseas markets to identify new opportunities. Going forward, we will need to continue strengthening these foundations, developing the capabilities required by a changing market, and translating them into actionable strategies. I am reminded of a phrase that stayed with me from MIPIM earlier this year: "Prepare, rather than predict." It is difficult to know precisely when the market will recover. What matters now is building the capabilities and positioning needed to turn opportunities in the next real estate investment cycle into tangible investment results. [Note: This article is based on meetings and discussions held during EXPO REAL 2026, with certain insights drawn from Green Street News' event coverage and interviews.] Reference: Green Street News, “Expo 2026: People are finally looking the beast in the eye”, 7 October 2026. Written by Sungeok (David) Chang, Head of IGIS Europe Edited by Soyeong Park, Brand Communication Manager ──────────── -This content has been prepared for informational purposes only and is not intended to serve as a basis for investment decision-making by users. It is not created for the purpose of promoting, soliciting, or recommending financial investment products, providing investment advice, or making stock recommendations. The company makes no express or implied representations or warranties regarding the accuracy or completeness of any materials or information provided in this content. Furthermore, the company assumes no responsibility or liability for any damages or losses incurred because of investment decisions made based on this content. Potential investors shall not raise any objections in this regard. -The above information is based on data as of October 2026 and has been prepared in compliance with applicable laws and internal control standards. The materials and information in this content are subject to change due to changes in market conditions, the stock market, interest rates, inflation, tax policies, and other social, economic, or policy-related factors. Additional risks may arise from asset price fluctuations, exchange rate volatility, credit rating downgrades, declines in real estate prices, investment performance results, or unforeseen natural disasters such as fires, floods, or pandemics. Consequently, financial (investment) products may result in partial or total loss of the principal investment, with such losses being borne by the investor. These products are not protected by the Korea Deposit Insurance Corporation under the Depositor Protection Act. Past performance does not guarantee future returns, and the results may differ from the performance at the time of content creation or in the future. Additional transaction and other costs may also apply. -This content has not been legally submitted or registered, nor has it been approved under any applicable law. It may contain subjective opinions that do not necessarily represent the official views or statements of the company. This content is not intended to solicit, offer, or recommend the subscription, purchase, or sale of securities. Investors have the right to receive sufficient explanations from financial product sellers in accordance with applicable laws. All investment decisions should be made carefully and solely on the information provided in the securities registration statement, (preliminary) investment prospectus, and terms and conditions. Investors should make prudent decisions based on their own judgment. [IGIS Asset Management Co., Ltd. Compliance Officer Review No. 900-26-Ad-103 (October 22, 2026 – October 21, 2027)]
26. 10. 23